What is the scope and market size of the Military Edge Computing Market?
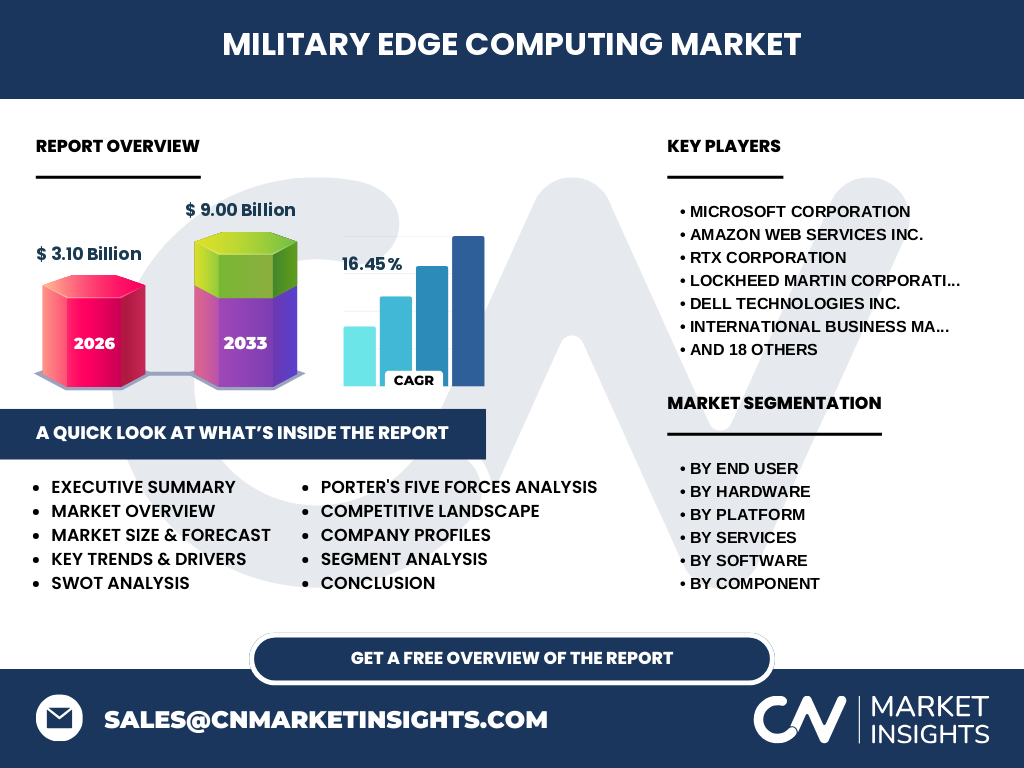
Our analysis indicates that the Military Edge Computing Market is valued at 3.10 Billion in 2026, driven by tactical data processing needs. This sector encompasses rugged hardware, specialized software, and deployment services critical for frontline operations. The industry significance lies in enabling real-time tactical decisions without relying on distant cloud centers.
Key market drivers, restraints, challenges, and opportunities shaping Military Edge Computing Market
Growth is propelled by the surge in autonomous drone telemetry and battlefield Internet of Things. However, supply chain constraints for semiconductor raw materials and strict defense certifications act as primary restraints. Opportunities abound for firms integrating artificial intelligence into tactical edge servers and gateways.
Emerging trends and growth patterns in Military Edge Computing Market
The shift toward decentralized battlefield intelligence is accelerating industry growth. Edge computing platforms are increasingly replacing legacy centralized command architectures. This transformation favors agile defense contractors capable of delivering low-latency processing directly to tactical platforms.
COVID-19 impact analysis on the Military Edge Computing Market
The pandemic severely disrupted global semiconductor supply chains, delaying ruggedized hardware shipments. Despite initial shocks, the recovery trajectory surged as defense agencies prioritized secure remote communications and resilient digital infrastructure, ultimately accelerating long-term modernization budgets.
Competitive benchmarking and strategic dynamics
Market concentration remains moderate to high, anchored by prime contractors like RTX Corporation and Lockheed Martin Corporation. Strategic dynamics involve aggressive mergers and acquisitions, with tech giants like Microsoft Corporation partnering with defense primes to integrate commercial cloud capabilities into tactical military hardware.
Executive summary of the Military Edge Computing Market
Our research projects the Military Edge Computing Market to expand from 3.10 Billion in 2026 to 9.00 Billion by 2033 at a 16.45% CAGR. Tactical edge solutions are transitioning from experimental deployments to core defense infrastructure requirements globally.
Market forecast from 2027 to 2033
The data suggests explosive growth, scaling the market from its 2026 baseline to 9.00 Billion by 2033. This robust 16.45% CAGR reflects sustained government investments in AI-driven command and control systems, demanding advanced edge servers and cybersecurity software.
Segmentation analysis across hardware, software, and services
The market segments into Component, Hardware (Processing Units, Ruggedized Computing), Software (AI and ML), Services (System Integration), Deployment Type (On Premises, Cloud, Hybrid), Platform (Land, Airborne, Naval), and End User (Defense, Government, Aerospace, Commercial). Hardware currently commands the largest share due to harsh environmental demands.
Regional market analysis and geographic distribution
North America dominates the geographic landscape due to substantial defense R&D budgets and early adoption of tactical cloud initiatives. Meanwhile, the Asia-Pacific region exhibits the fastest growth trajectory, driven by escalating regional security tensions and indigenous military modernization programs.
In-depth regional review of operational constraints
Regional performance is heavily influenced by localized export controls, such as ITAR regulations in the United States. European markets emphasize interoperability across allied NATO forces, prioritizing standardized edge networking equipment and sovereign cybersecurity frameworks.
Company profiles and strategic positioning
Industry leaders leverage distinct competitive moats. NVIDIA Corporation dominates processing units, while Amazon Web Services Inc. and Microsoft Corporation capture cloud-to-edge software demand. Traditional primes like Northrop Grumman Corporation and General Dynamics Corporation excel in platform integration.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers is high, dominated by well-funded government defense agencies. Threat of new entrants remains low due to stringent military-grade certification hurdles, specialized intellectual property, and high capital expenditure requirements for ruggedized manufacturing facilities.
SWOT analysis of the Military Edge Computing sector
Strengths include ultra-low latency processing and robust battlefield resilience. Weaknesses involve high initial deployment costs. Opportunities lie in commercial-off-the-shelf dual-use tech adaptations, while threats center on sophisticated cyber-attacks targeting edge nodes.
Value chain analysis from raw materials to end-users
The value chain initiates with rare-earth mineral extraction and semiconductor wafer fabrication, progressing to ruggedized hardware assembly by firms like Curtiss-Wright Corporation. Software integration and system deployment follow before final delivery to defense and aerospace end-users.
Investment insights and strategic recommendations
High-potential investment areas target artificial intelligence software and zero-trust cybersecurity frameworks. Stakeholders should prioritize partnerships with established prime defense contractors to secure long-term procurement contracts within command and control system upgrades.
Conclusion and key takeaways for stakeholders
Reaching 9.00 Billion by 2033, the market presents lucrative opportunities for agile innovators. Success depends on delivering scalable, secure, and ruggedized edge computing solutions that seamlessly integrate across land, airborne, and naval platforms.
Research methodology for baseline estimations
Our estimates are triangulated using a rigorous mix of primary stakeholder interviews with defense technologists, secondary analysis of government procurement budgets, and trade registry data tracking semiconductor and rugged hardware shipments.
Scope of the report and coverage parameters
This report covers global military edge computing deployments across hardware, software, services, and platform types through 2033. Limitations include restricted access to classified black-budget military programs and proprietary internal supply chain data.
Recent developments, partnerships, and strategic moves
Recent industry momentum is defined by major tech-defense alliances, such as contracts awarded to Leidos Holdings Inc. and Booz Allen Hamilton Holding Corp. for tactical cloud integration. Companies are aggressively launching AI-optimized edge servers to meet surging frontline demands.